A past VA purchase originated through Mike Alkema reached clear to close in eight days. This is a past result, not a promise. Every borrower, property, contract and underwriting review is different.
The recognition behind the eight-day milestone
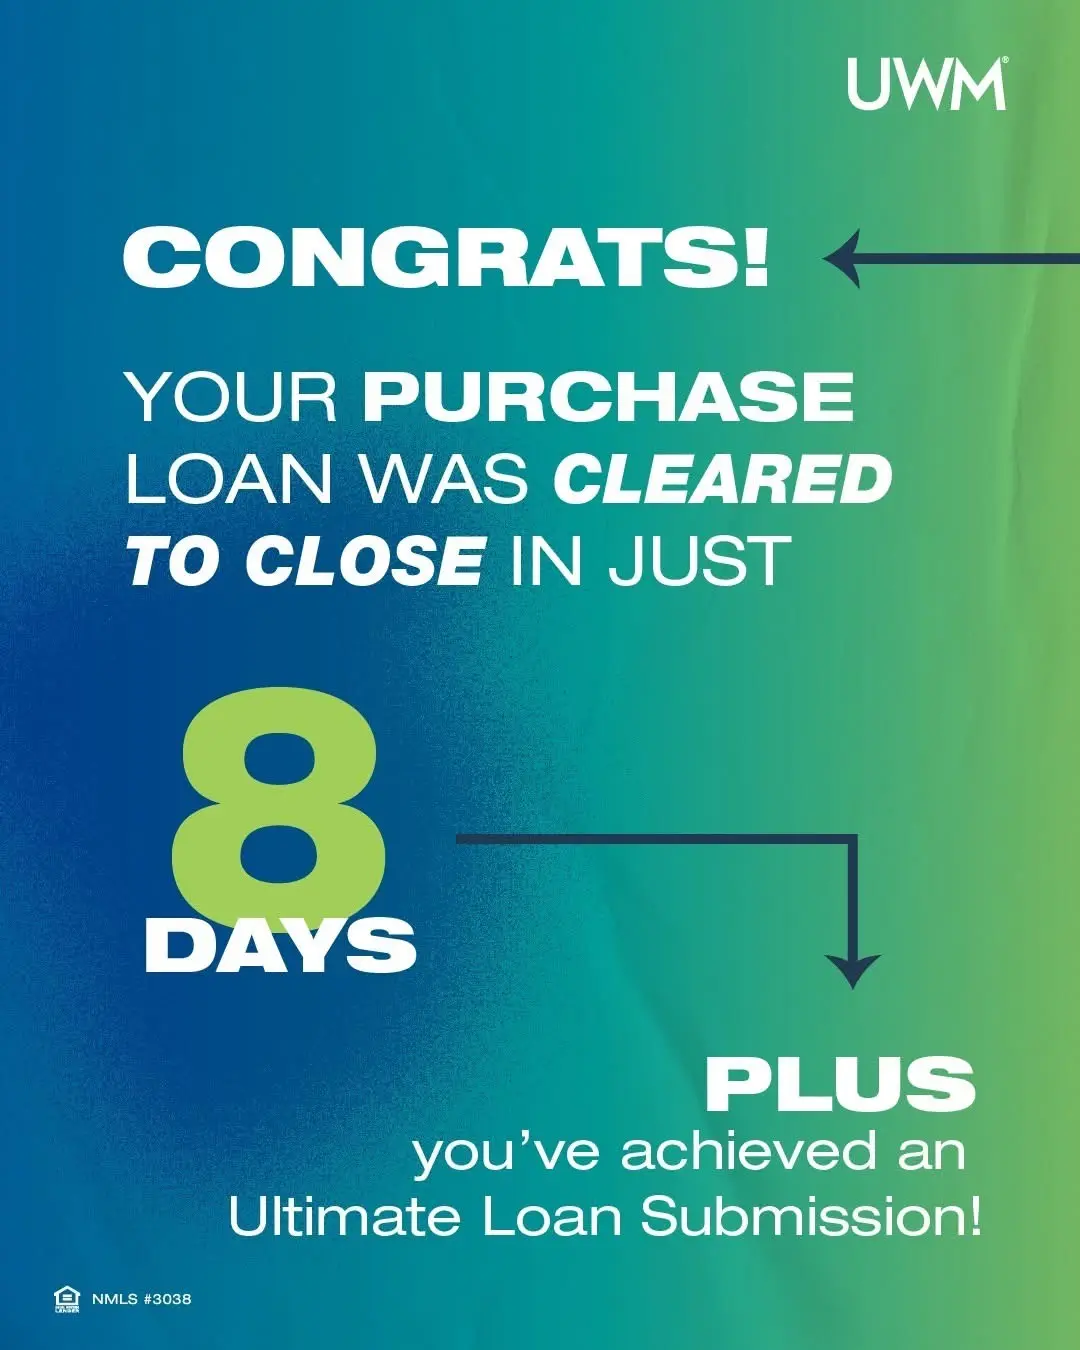
The recognition states that the purchase loan was cleared to close in eight days and received an “Ultimate Loan Submission” designation. It does not identify the starting date, state whether the count uses calendar or business days, or establish the final funding date. Those details should not be inferred from the graphic.
The preparation steps below are guidance for another buyer, not a reconstruction of this borrower’s private loan file.
What “clear to close” means
Clear to close generally means the lender has completed the required underwriting review and cleared the conditions needed to prepare for closing. It does not mean the borrower should assume funding is complete, and it does not remove the need for final documents, signatures, title work or other closing steps.
The eight-day milestone is useful because it shows what coordinated preparation can accomplish in one specific file. It should be read as a process example rather than a standard timeline.
Preparation lessons for your own purchase
Income, asset, identity and service-related documentation must be collected and reviewed promptly. Missing pages or unexplained deposits can slow any mortgage.
Retrieving and reviewing the Certificate of Eligibility early can reveal entitlement or prior-use questions before they delay underwriting.
The borrower, Realtor, lender, title company and appraiser need accurate information and timely responses.
How a VA buyer can prepare
- Provide complete documents rather than screenshots or partial statements.
- Avoid opening new credit or moving unexplained funds without discussing it first.
- Keep homeowners-insurance and property questions moving as soon as the offer is accepted.
- Respond quickly when underwriting requests clarification or updated records.
- Review the payment and cash-to-close plan before the final figures arrive.
Speed should never replace accuracy. The objective is a well-prepared file with fewer preventable delays.
What this result does and does not establish
It demonstrates that a VA purchase can move efficiently when the facts and participants line up. It does not establish an average, guarantee that another transaction will follow the same timing, or predict appraisal, title or underwriting outcomes.
Borrowers who are comparing lenders should ask who will manage the file, how quickly questions are answered, what documentation has already been reviewed and how the lender will communicate with the agents.
Connect the timeline to the mortgage strategy
A fast process is valuable only when the loan also fits the borrower. Review rate, points, credits, estimated payment and cash to close with the same care as the timeline. Mike’s Mortgage Coach comparison can present those tradeoffs side by side.
Mortgage Loan Originator · NMLS #642953 · Leeward Point Mortgage LLC, Company NMLS #1823590. More than 30 years of mortgage experience. Reviewed September 3, 2026.
Have a closing date in mind?
Tell Mike your Michigan purchase location, whether you already have an accepted offer, and the date you hope to close. A conversation can help identify the questions that need answers before anyone commits to a schedule.
Mike, can we talk about timing?Start with the Michigan VA guide or the VA loan checklist.